
Important: Weeb Pakistan is an independent news website, not a government website. Confirm details on the official website or helpline of the program. Never share your CNIC, PIN or OTP with anyone, and never pay anyone to receive a government payment. Report an error.
Meezan Bank Easy Home 2026 Details
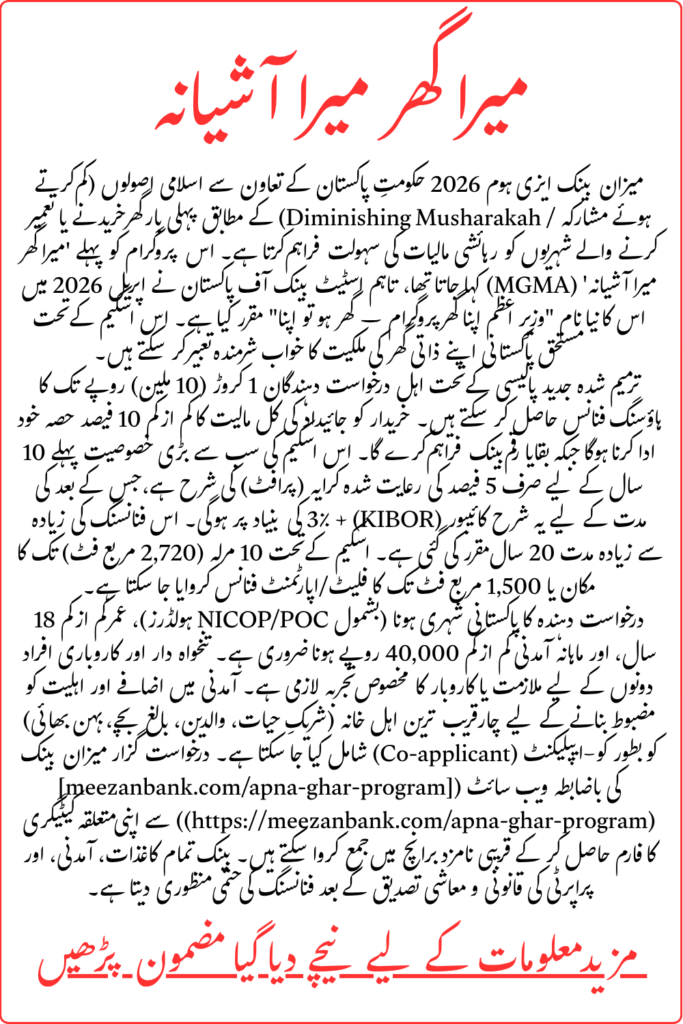
Meezan Bank Easy Home 2026 provides a Shariah-compliant way for eligible Pakistanis to finance a home through the government’s subsidized housing finance program. The scheme was initially introduced as Mera Ghar Mera Ashiana, but the State Bank of Pakistan announced its new name in April 2026: Wazir-e-Azam Apna Ghar Program – Ghar Ho Tu Apna. Meezan Bank offers this facility through its Islamic home financing product.
Under the revised program, eligible applicants can obtain financing of up to Rs. 10 million, contribute at least 10% of the property value, and benefit from a 5% rental rate for the first 10 years. The maximum financing period is 20 years.
These updated terms replace the older information about Rs. 2 million and Rs. 3.5 million financing tiers and separate 5% and 8% rates. Applicants should confirm their individual eligibility and final payment plan with Meezan Bank before applying.
Meezan Bank Easy Home and the Government Housing Scheme
Meezan Bank Easy Home is an Islamic home financing product that allows customers to purchase a residential property or finance an eligible home construction project. Its financing structure is based on Diminishing Musharakah, a partnership arrangement in which the bank and customer jointly own the financed property.
The government’s subsidized housing program aims to make homeownership more affordable by reducing the financing cost for eligible applicants. The scheme was previously known as Mera Ghar Mera Ashiana. In March 2026, the government approved revised features, including a higher financing limit and a uniform 5% end-user pricing rate. The State Bank of Pakistan subsequently directed participating financial institutions to use the new program name, Wazir-e-Azam Apna Ghar Program – Ghar Ho Tu Apna.
Meezan Bank provides the facility according to its Islamic financing framework and the program’s applicable conditions. Applicants should use the bank’s current scheme page and application forms rather than relying on older advertisements or outdated articles.
Also Read: NADRA Introduces Automated Machines
Meezan Bank Easy Home 2026 Quick Overview
The following table summarizes the main features published by Meezan Bank for the subsidized housing finance facility.
| Feature | Current details |
|---|---|
| Official scheme name | Wazir-e-Azam Apna Ghar Program – Ghar Ho Tu Apna |
| Former name | Mera Ghar Mera Ashiana |
| Participating bank | Meezan Bank |
| Maximum financing | Up to Rs. 10 million |
| Minimum customer contribution | 10% of property value |
| Rental rate | 5% for the first 10 years |
| Rate after 10 years | Variable, based on KIBOR + 3% |
| Maximum financing tenure | 20 years |
| Eligible applicants | First-time homeowners meeting the bank’s criteria |
| House size | Up to 10 marla or 2,720 square feet |
| Flat or apartment size | Up to 1,500 square feet |
| Application method | Through Meezan Bank’s designated branches and application process |
These are the published scheme features, not a guarantee that every applicant will receive the maximum amount. The bank assesses income, repayment capacity, property documents, and other applicable requirements before approving financing.
What Is the Maximum Loan Amount Under the Scheme?
Meezan Bank’s current program page states that eligible customers can receive housing finance of up to Rs. 10 million (Rs. 1 crore). This is higher than the original MGMA limits published in 2025, which provided financing of up to Rs. 2 million under Tier 1 and up to Rs. 3.5 million under Tier 2.
The revised government framework approved in February 2026 increased the financing limit and introduced a uniform 5% end-user pricing rate. As a result, readers should not use the old Tier 1 and Tier 2 limits when checking the updated Meezan Bank offer.
The amount approved for an individual depends on the property’s value, the applicant’s income, existing financial obligations, and the bank’s credit assessment. Applying for Rs. 10 million does not mean that the full amount will automatically be approved.
Profit Rate and Monthly Installments
One of the main benefits of the revised housing program is its subsidized rental rate. Meezan Bank lists a 5% rate for the first 10 years, followed by a variable rate based on one-year KIBOR plus 3% for the remaining financing period, subject to the applicable terms.
Because Meezan Bank uses Diminishing Musharakah, its home financing is structured around shared property ownership and rental payments rather than a conventional interest-based loan. The bank’s share decreases as the customer purchases additional ownership units over time.
Your monthly payment will depend on the amount financed, the financing tenure, the property, and the terms approved by the bank. It is better to request an individual payment schedule than to rely on an estimated installment copied from another applicant’s case.
How Much Down Payment Is Required?
The published program requires a minimum customer contribution of 10% of the property value. This means that the customer must provide part of the purchase price from their own funds, while the bank finances the eligible remaining amount, subject to approval.
For example, if a property is valued at Rs. 5 million, a 10% contribution would equal Rs. 500,000. This is only a simple illustration; the actual contribution and eligible financing amount depend on the bank’s valuation and approval.
Applicants should also ask about legal report charges, property valuation charges, documentation costs, and any other applicable expenses. Meezan Bank lists no processing charge for the scheme, but other charges may apply according to its published schedule.
Also Read: 8171 Tracking Portal Restoration
Eligibility Criteria for Meezan Bank Easy Home 2026
Applicants must satisfy the government program’s conditions as well as Meezan Bank’s financing and credit requirements. The bank’s current program page lists the following key criteria.
Citizenship and Homeownership
The program is designed for first-time homeowners. Meezan Bank lists resident Pakistani nationals holding a valid CNIC and eligible non-resident Pakistanis holding valid NICOP or POC documents under its published criteria.
Applicants must meet the scheme’s first-time homeownership requirement. If you already own a residential property, do not assume that you qualify. Confirm your circumstances with the bank before submitting an application.
Age Requirements
Meezan Bank’s published qualification criteria state that the applicant and co-applicant must generally be at least 18 years old. The maximum age at financing maturity depends on the applicant’s category and whether a co-applicant’s income is combined with the applicant’s income.
For applicants whose income is clubbed with a co-applicant, the published maximum age at maturity is generally 65 years. For a co-applicant without income clubbing, the bank lists a maximum age of 70 years. For salaried applicants, the applicable retirement-age condition may also affect eligibility.
Since age rules can depend on employment type and application structure, confirm the exact limit with Meezan Bank before applying.
Minimum Income and Employment Conditions
Meezan Bank lists a minimum gross monthly income of Rs. 40,000 for individuals under its published qualification criteria. Meeting this minimum does not guarantee approval because the bank also evaluates whether the applicant can afford the proposed installments.
For salaried applicants, the bank lists the following employment history requirements:
- Permanent employees should generally have at least six months of continuous work history in the same industry or field.
- Contractual employees should generally have at least one year of continuous work history in the same industry or field and two years of total experience.
- Self-employed applicants and business owners should generally have at least two years in their current business or industry.
The bank may request income evidence, employment details, bank statements, or business records to verify the information provided.
Co-Applicant and Income Clubbing
Meezan Bank allows eligible immediate family members to participate as co-applicants under its published criteria. These may include a spouse, parents, adult children, brothers, or sisters.
The bank states that income clubbing can be allowed for up to four co-applicants, subject to its requirements. Combining eligible family income may strengthen an application, but the bank must assess all applicants and their financial obligations.
Property Size and Financing Purposes
The revised scheme allows larger residential units than the original 2025 framework. Meezan Bank’s current program page lists the following property size limits:
- House: Up to 10 marla or 2,720 square feet.
- Flat or apartment: Up to 1,500 square feet.
Meezan Bank also lists no maximum property price cap on its program page. However, this does not mean that any property will automatically qualify. The property must meet the bank’s legal, valuation, residential-use, and financing conditions.
The bank’s housing finance products include options for purchasing a constructed residential property and eligible construction cases. Customers planning to buy a plot and construct a house, or build on land they already own, should confirm which financing category applies to their project before proceeding.
Also Read: Chief Minister Punjab Minority Card 2026 Complete Online Registration Guide
How to Apply for Meezan Bank Easy Home 2026
Applicants should follow the bank’s current application process and use the relevant form for their income category. Meezan Bank publishes separate forms for formal salaried applicants, formal business applicants, and applicants with informal income.
Step 1: Check Your Eligibility
Before visiting a branch, review the current program conditions. Check your citizenship documents, first-time homeownership status, income, age at maturity, employment history, and the size of the proposed property.
You should also estimate the contribution you can afford and review your existing financial commitments. This preparation can help you discuss a realistic financing amount with the bank.
Step 2: Obtain the Correct Application Form
Visit a Meezan Bank branch designated for the program or use the official scheme page to locate the relevant application form. Choose the form that matches your income and employment category.
Do not submit an outdated form from an unofficial website. Scheme names, financing limits, and application requirements may change, so use the bank’s latest instructions.
Step 3: Prepare Your Documents
The bank will tell you which documents are required for your specific application. Depending on your category and circumstances, these may include:
- Valid CNIC, or eligible NICOP/POC documentation.
- Income and employment evidence.
- Salary slips or relevant business and self-employment records.
- Bank statements and other financial information requested by the bank.
- Property ownership and legal documents.
- Co-applicant documents, if applicable.
- Additional forms or declarations requested during verification.
This is a general preparation list, not an exhaustive official checklist. Ask the branch for the current document requirements before submitting your application.
Step 4: Submit the Application
Complete the application form accurately and provide the supporting documents. Make sure your income, employment details, property information, and contact details are consistent across the application and supporting records.
Keep a copy of the application and any documents submitted. Ask the bank how you can follow up on your case and whether any additional information is required.
Step 5: Complete Bank Verification
Meezan Bank will assess your application under its financing policy and the scheme’s conditions. This can include reviewing income, repayment capacity, credit history, and property documents.
The bank may request clarification or further documentation. Responding promptly can help prevent avoidable delays, but approval depends on the bank’s assessment.
Step 6: Property Assessment and Approval
The bank evaluates the proposed property and completes the required legal and valuation checks. If the application satisfies the applicable requirements, the bank explains the approved financing amount, customer contribution, rental rate, payment schedule, and contractual conditions.
Read the offer and financing documents carefully before signing. Ask the bank to explain any charge, payment condition, or clause that you do not understand.
Benefits of Meezan Bank Easy Home 2026
The program may help eligible first-time homeowners who need financing to purchase or construct a residential property. Its main benefits include:
- Subsidized 5% rental rate for the first 10 years under the published program terms.
- Financing of up to Rs. 10 million for eligible applicants.
- A maximum financing period of 20 years.
- A minimum customer contribution of 10% of the property value.
- Islamic financing through Meezan Bank’s Diminishing Musharakah structure.
- Published property size limits of up to 10 marla for houses and 1,500 square feet for flats or apartments.
- No processing charge listed by Meezan Bank for the scheme, although other applicable charges may apply.
The most suitable financing option depends on the applicant’s income, budget, property, and ability to meet payments over the full financing period.
Also Read: Complete Details of BISP Survey Registration Requirements For New Applicants In 2026
Official Website and Application Information
For the most reliable information, visit the official Meezan Bank scheme page:
Meezan Bank Wazir-e-Azam Apna Ghar Program: https://www.meezanbank.com/apna-ghar-program/
The page provides the current product features, eligibility criteria, application forms, payment calculator, and designated branch information. You can also review the State Bank of Pakistan’s official website for program notifications and policy updates.
Use official bank channels to confirm your eligibility and submit your application. Do not pay an agent who promises guaranteed approval or asks for money to secure a government subsidy.
Final Words
Meezan Bank Easy Home 2026 gives eligible first-time homeowners an opportunity to explore Islamic housing finance under the government’s revised subsidized housing program. The facility now operates under the name Wazir-e-Azam Apna Ghar Program – Ghar Ho Tu Apna, replacing the earlier Mera Ghar Mera Ashiana name.
Meezan Bank lists financing of up to Rs. 10 million, a minimum 10% customer contribution, a 5% rental rate for the first 10 years, and a maximum tenure of 20 years. However, the amount you receive and the terms of your payment plan depend on the bank’s assessment and the current program rules. Review the official requirements, prepare your documents, and contact a designated Meezan Bank branch before making a financial commitment.
FAQs
What is the maximum financing amount under Meezan Bank Easy Home 2026?
Meezan Bank lists maximum financing of up to Rs. 10 million under the Wazir-e-Azam Apna Ghar Program – Ghar Ho Tu Apna. The amount approved depends on the applicant’s eligibility, income, property, and bank assessment.
What is the rental rate under the scheme?
Meezan Bank lists a 5% rental rate for the first 10 years. For subsequent years, the published rate is variable and based on KIBOR plus 3%, subject to the applicable terms.
Who can apply for Meezan Bank Easy Home?
Eligible first-time homeowners who meet the citizenship, age, income, employment, property, and other bank requirements may apply. Meeting the basic conditions does not guarantee approval.
How much down payment is required?
The program lists a minimum customer contribution of 10% of the property value. The bank will confirm the exact amount required for the property and financing case.
What is the current name of the Mera Ghar Mera Ashiana scheme?
The State Bank of Pakistan announced in April 2026 that the scheme was renamed the Wazir-e-Azam Apna Ghar Program – Ghar Ho Tu Apna. Meezan Bank offers its subsidized Islamic housing finance facility under this name.