
Important: Weeb Pakistan is an independent news website, not a government website. Confirm details on the official website or helpline of the program. Never share your CNIC, PIN or OTP with anyone, and never pay anyone to receive a government payment. Report an error.
Mera Ghar Mera Ashiana Scheme 2026
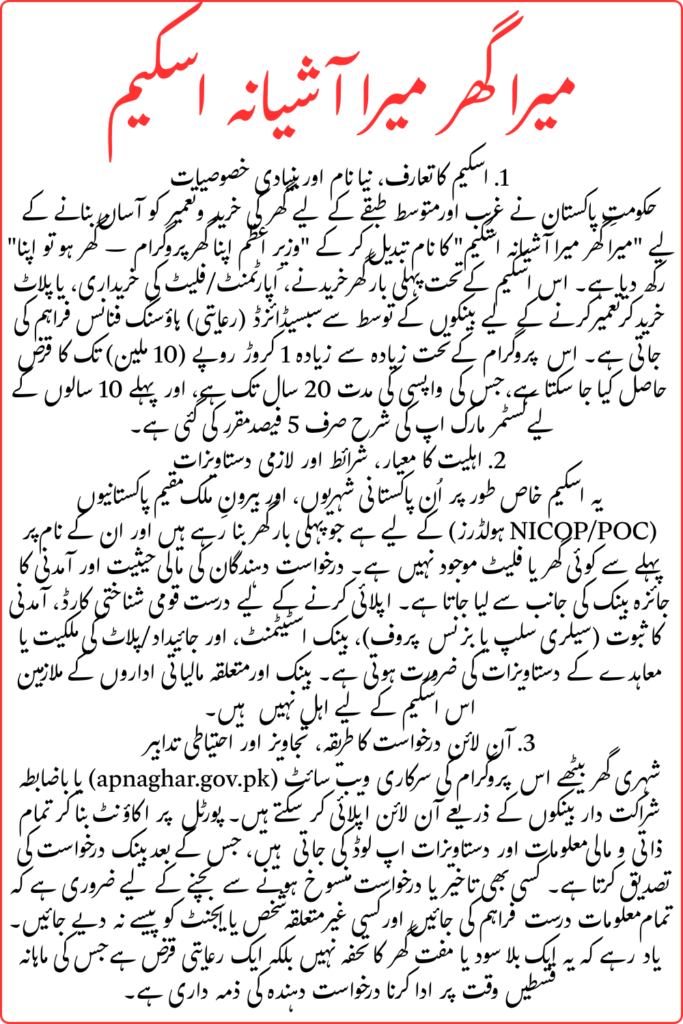
Buying a house is difficult for many Pakistani families because property prices and construction costs are high. To make homeownership more affordable, the Government of Pakistan introduced the Mera Ghar Mera Ashiana Scheme. The programme named as Wazir-e-Azam Apna Ghar Program – Ghar Ho Tu Apna.
The programme provides subsidised housing finance to eligible first-time homebuyers. Applicants can apply to purchase a house or flat, construct a house, or purchase a plot and build a house, subject to the programme’s conditions.
you will learn here about the October 2026 update, loan limits, eligibility criteria, required documents, and the online registration process.
Overview of Mera Ghar Mera Ashiana Scheme 2026
The Mera Ghar Mera Ashiana Scheme was introduced to help eligible citizens finance their first home. Its current official name is Wazir-e-Azam Apna Ghar Program – Ghar Ho Tu Apna.
The programme operates through the official online portal and participating financial institutions. The State Bank of Pakistan provides the relevant banking instructions.
| Detail | Information |
|---|---|
| Previous name | Mera Ghar Mera Ashiana |
| Current name | Wazir-e-Azam Apna Ghar Program – Ghar Ho Tu Apna |
| Main purpose | Affordable housing finance |
| Maximum financing | Up to Rs. 10 million |
| Maximum repayment period | Up to 20 years |
| Subsidised markup | 5% for the first 10 years |
| Borrower’s contribution | Generally at least 10% of the eligible property cost |
| Official portal | https://apnaghar.gov.pk/ |
| SBP website | https://www.sbp.org.pk/ |
The final loan amount depends on eligibility, the property’s value, income assessment, and the programme’s applicable conditions.
Also Read: Kisan Card Phase 2 Check Status Online Using CNIC Complete Guide for Farmers 2026
Purpose of the Scheme
The main purpose of this programme is to help people who cannot easily afford a house through regular housing finance.
Many families spend a large part of their income on rent and struggle to save enough money to buy property. Subsidised housing finance can help eligible applicants spread the cost of homeownership over several years.
The main objectives include:
- Making homeownership more affordable for eligible families.
- Providing subsidised housing finance through participating institutions.
- Supporting house construction and property purchases.
- Reducing the initial financial burden on homebuyers.
- Encouraging construction activity and employment.
The programme provides a loan, not a free house or unconditional cash assistance. Approved applicants must repay their financing according to the agreed terms.
Features of the Scheme
The programme includes several features intended to make housing finance more accessible.
Financing up to Rs. 10 million: Eligible applicants may qualify for financing of up to Rs. 1 crore, depending on the bank’s assessment and applicable programme rules.
Subsidised markup: The programme provides a fixed 5% customer markup rate for the first 10 years under the published current framework.
Long repayment period: The maximum repayment period is 20 years, allowing eligible borrowers to spread their payments over a longer period.
Lower initial contribution: The financing arrangement generally allows up to 90% of the eligible property value to be financed, with the borrower contributing at least 10%.
No processing fee: The programme’s published terms provide for no processing fee and no prepayment penalty.
Different housing options: Eligible applicants can seek financing to purchase a house or flat, construct a house on an existing plot, or purchase a plot and construct a house.
These features are subject to the current programme rules and the participating institution’s assessment.
Also Read: BISP Office Timings Update 2026 New Schedule and Visiting Hours Full Guide
Loan Details and Markup Rates
Under the revised programme, eligible applicants can obtain housing finance of up to Rs. 10 million. The customer markup rate is 5% for the first 10 years, while the remaining repayment period may be subject to the applicable market rate. The maximum repayment period is 20 years.
| Loan detail | Current programme information |
|---|---|
| Maximum loan | Rs. 10 million |
| Customer markup | 5% for the first 10 years |
| Maximum repayment period | 20 years |
| Borrower’s contribution | At least 10% of eligible property value |
| Processing fee | No processing fee under programme terms |
| Early repayment | No prepayment penalty under programme terms |
For example, if a property is valued at Rs. 5 million and the bank approves financing for 90% of its eligible value, the loan would be Rs. 4.5 million. The buyer would contribute Rs. 500,000.
This is only an example. The bank determines the eligible property value, approved loan, repayment schedule, and applicable conditions.
Eligibility Criteria
The programme is intended for eligible first-time homebuyers who meet its identity, property, and financing requirements.
Before applying, check the following conditions:
- Pakistani citizenship: Applicants must meet the applicable citizenship and identity requirements.
- Valid identification: A valid CNIC or other accepted identity document is required.
- First-time homeownership: Applicants must not already own a house or flat in their name under the programme’s eligibility conditions.
- Repayment ability: The bank assesses income and existing financial obligations.
- Eligible property: The proposed house, flat, or construction project must meet the programme’s requirements.
- Document verification: The applicant’s personal and financial information must be verified.
The programme also allows eligible overseas and non-resident Pakistanis holding NICOP or POC to obtain financing under the applicable rules. However, employees of banks and other covered financial institutions are not eligible under the relevant September 2026 clarification.
Always check the latest eligibility requirements before submitting your application.
Documents Required
Preparing your documents before applying can help prevent delays during verification. The exact requirements depend on your income source, identity status, and proposed property.
Commonly requested documents include:
- Valid CNIC, NICOP, or other applicable identity document.
- Salary slips or proof of business income.
- Bank statements, if requested.
- Property ownership documents or a sale agreement.
- Plot documents and construction details, where applicable.
- Application forms and declarations requested by the bank.
Salaried applicants may need employment and salary records. Self-employed applicants may need business and income evidence. Overseas applicants should ask their selected institution which additional documents are required.
Use the official checklist provided by the programme or participating institution rather than relying on an outdated list.
Also Read: FBR Extends Income Tax Return Deadline to October 31, 2026: Who It Covers and How
How to Apply Online for Mera Ghar Mera Ashiana Scheme 2026
The programme has an official online portal where eligible applicants can check requirements and submit housing finance applications. You can also apply through participating financial institutions.
Follow these steps to apply online.
Step 1: Visit the official portal
Open https://apnaghar.gov.pk/ in your browser. Make sure the website address is correct before entering personal information.
Step 2: Check your eligibility
Read the eligibility requirements and confirm that you meet the programme’s conditions before starting your application.
Step 3: Create an account
If you are a new applicant, follow the portal’s instructions to create an account and verify your identity.
Step 4: Complete the application form
Log in and enter the requested personal, income, and property information. Check your details carefully before proceeding.
Step 5: Upload the required documents
Provide the documents requested by the portal, such as identification, income evidence, and property information.
Step 6: Submit your application
Review your information and submit the completed application. Save any reference number or confirmation provided by the system.
Step 7: Wait for bank verification
Your selected participating institution will review your application, verify the documents, and assess your repayment ability.
Step 8: Check your application status
Log in to the official portal or follow the instructions provided by your selected institution to track your application.
Submitting an application does not guarantee approval. The final decision depends on the programme requirements and the bank’s assessment.
What Will Happen After Loan Approval
After your application is approved, the participating institution explains the financing agreement and the next steps.
Before signing, make sure you understand:
- The total approved loan amount.
- Your required initial contribution.
- The monthly instalment and repayment schedule.
- The markup rate and subsidy period.
- Any applicable legal, property, or other charges.
- The conditions for releasing the funds.
Financing is released according to the approved purchase or construction arrangement. It is not necessarily paid to the applicant as unrestricted cash.
Remember that the government subsidy does not remove your responsibility to repay the loan. Review the agreement carefully and ensure that the monthly instalments fit your budget.
Also Read: PM Apna Ghar Scheme Apply Online With Just 5 Documents And Get Approval in 15 Days
Common Mistakes to Avoid
Some applicants experience delays because their documents are incomplete or their information does not match the bank’s records.
Avoid these common mistakes:
- Entering incorrect CNIC or personal information.
- Providing incomplete income documents.
- Submitting incorrect property details.
- Assuming that registration guarantees loan approval.
- Ignoring messages or requests from the bank.
- Applying through unofficial websites or agents.
- Signing an agreement without understanding its terms.
Always use the official programme portal or a participating financial institution. Do not pay an unauthorised person who promises guaranteed approval.
Tips for a Successful Application
A well-prepared application can make the verification process easier.
- Keep your identity documents valid and up to date.
- Prepare your income and bank records before applying.
- Confirm that your property meets the programme requirements.
- Calculate your expected monthly expenses before choosing a loan.
- Review the markup and repayment conditions carefully.
- Save your application confirmation and reference number.
- Respond promptly if the bank requests additional information.
Approval depends on the bank’s assessment and the programme’s rules. Accurate information can help prevent avoidable delays, but it cannot guarantee approval.
Importance of the Scheme for Pakistani Families
Affordable housing finance can help eligible families move towards homeownership without paying the entire property cost upfront.
A longer repayment period allows borrowers to spread payments over time. Subsidised markup can also reduce financing costs during the applicable subsidy period.
The programme may support the construction sector and create demand for building materials, skilled workers, and related services.
However, a housing loan is a long-term financial commitment. Applicants should consider their income stability, household expenses, and ability to make regular payments before accepting an offer.
Also Read: Honahar Scholarship Laptop Distribution District Wise Check List Of Eligible Students
Conclusion
The Mera Ghar Mera Ashiana Scheme is now officially known as the Wazir-e-Azam Apna Ghar Program. The revised programme provides subsidised housing finance of up to Rs. 10 million, with a 5% customer markup rate for the first 10 years and a repayment period of up to 20 years, subject to applicable conditions.
If you want to apply in October 2026, visit the official portal at https://apnaghar.gov.pk/, check your eligibility, prepare the required documents, and complete the application instructions.
Use only official channels, review the financing agreement carefully, and make sure you can comfortably afford the repayments before accepting a housing loan.
FAQs
What is the Mera Ghar Mera Ashiana Scheme 2026?
It is a housing finance programme now known as Wazir-e-Azam Apna Ghar Program – Ghar Ho Tu Apna. It helps eligible applicants finance their first home through participating institutions.
How can I apply for the scheme online?
Visit the official portal at https://apnaghar.gov.pk/ and follow the application instructions. You can also contact a participating bank for assistance.
What is the maximum loan amount under the scheme?
Eligible applicants may qualify for financing of up to Rs. 10 million, subject to programme rules and bank approval.
What is the markup rate under the programme?
The programme offers a 5% customer markup rate for the first 10 years under its published terms. Confirm the applicable conditions with your participating bank.
Who is eligible for the housing scheme?
The programme is designed for eligible first-time homebuyers who meet the identity, property, and income requirements. Final eligibility depends on the current rules and the bank’s assessment.